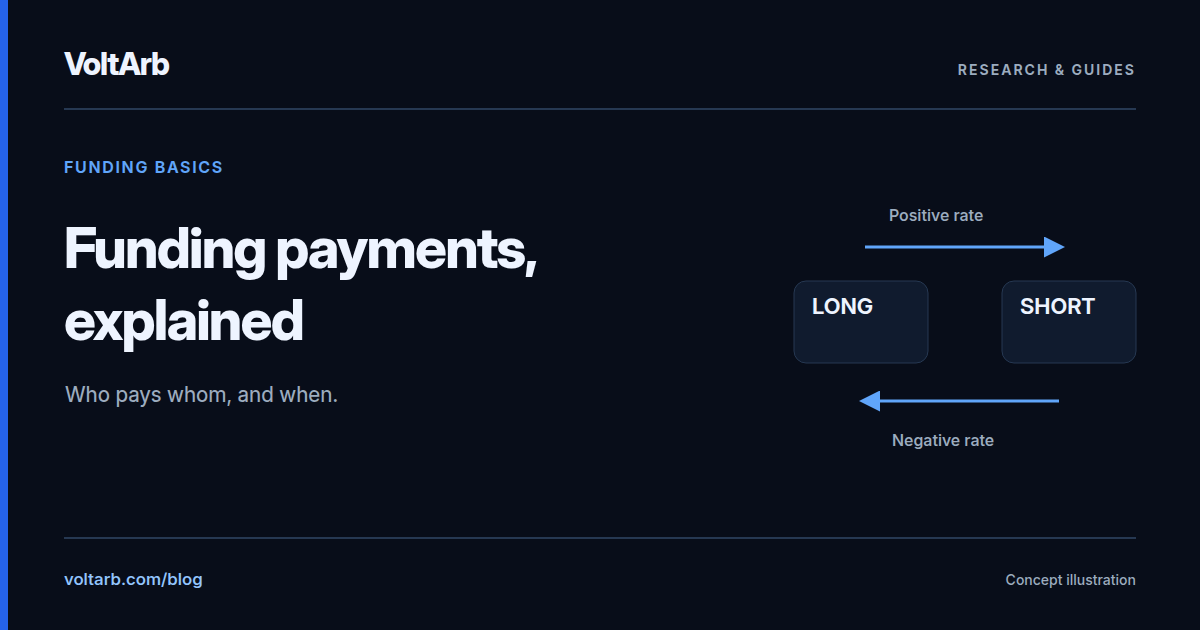
The Problem Funding Rate Solves
A perpetual contract has no scheduled expiry to bring its price towards spot. A position can remain open while exchange requirements are met and the contract continues trading.
Funding creates incentives that help keep the perpetual price close to the underlying asset price: one side pays the other. It does not guarantee identical prices at every instant.
How It Works
Each contract has its own funding schedule. The examples below state the interval explicitly; a funding quote should not automatically be treated as an eight-hour rate.
Longs pay shorts. Contract rules determine the rate, which can include a premium to the index and an interest component.
Shorts pay longs. The rate sign determines the payment direction, but does not by itself predict a price move.
For a linear contract, the payment equals the position value under exchange rules multiplied by the settlement rate. Illustrative example: at $10,000 notional and +0.01%, the long pays $1.00 for one settlement and a short of the same notional receives $1.00.
Check which price is used to value the position and which currency settles the payment. Linear and inverse contract rules differ, for example.
The Numbers That Matter
For an illustrative calculation, fix the long notional at $10,000 and the rate at +0.01% every 8 hours. Assume the position participates in every settlement. These are example assumptions, not a claim about a normal market rate.
With those assumptions unchanged, payments simply add up. This example has no reinvestment or compounding.
$90 is 0.9% of the assumed $10,000 notional. A different settlement count, rate or notional produces a different total.
If an assumed +0.10% eight-hour rate persists for three settlements, the long pays 0.30% of an unchanged notional over a day.
At −0.10% for the same period, the short is the payer. These are arithmetic scenarios, not rate limits or forecasts.
Funding and the Effect on Margin
Illustrative long: $1,000 initial margin, $10,000 notional and 10x leverage. Hold the notional constant at every settlement and assume a +0.15% eight-hour rate.
The payment is $15 per settlement, or 1.5% of initial margin. Three settlements cost $45; nine cost $135, or 13.5% of initial margin. These amounts exclude price P&L and trading fees.
See the leverage guide for the relationship between notional and margin. A leverage setting alone does not determine position safety.
For an unchanged notional, changing the leverage setting does not change the funding cash payment. It changes initial margin requirements and the payment as a share of that margin. If funding is deducted from margin, the liquidation buffer can shrink.
How Different Exchanges Handle Funding
Compare the rate together with its interval, next settlement and position valuation rules. Bybit intervals can differ across trading pairs and change; Hyperliquid pays funding every hour.
Hyperliquid documentation defines an eight-hour rate formula, while each hourly payment uses one eighth of the corresponding value. Check whether a data field shows the payment rate or a rate normalized to another period.
A +0.08% eight-hour rate and a +0.02% hourly rate are not payments for the same time span. With constant rates and notional, eight hourly settlements total 0.16%, versus 0.08% for one eight-hour settlement. In a real trade, sum actual payments over the holding period. See the cross-exchange funding guide.
How to Interpret a Funding Rate
Consider funding alongside the price basis, liquidity and contract history. The rate alone is insufficient to establish the future price direction.
Check the futures premium to the index and the exchange formula. A positive rate alone does not imply an inevitable price decline.
Check the discount and hedging costs. A negative rate does not guarantee a rebound or an attractive entry.
Compare it with the same contract history over equal periods. A 0.01% rate is not a universal sign of a neutral market.
Funding Rate in Arbitrage
For each setup, separate funding payments, price P&L and other costs.
You buy spot and open a futures short. Price P&L depends on the difference between entry and exit spreads. At a positive settled rate, the short receives funding; that rate can change before settlement. The spot position needs separate capital.
Check contract availability, fees, liquidity and the conditions that apply to your account.
A long on one exchange and a short on another have separate payments. Sum amounts received minus amounts paid on both positions over the same holding window. Simply subtracting rates only applies with equal notionals and comparable settlement periods.
Positive funding cash flow can be outweighed by spread changes and the costs of opening and closing.
The intended cash flow is funding payments. An opposite position reduces directional exposure, but both sides need execution, contract and collateral checks.
Illustrative example with the same settlement period: a $500 long at −0.10% receives $0.50, while a $500 short at +0.04% receives $0.20. Total funding is +$0.70. This is cash received before fees and spread changes, not net profit or the return on committed capital.
What to Look For
When evaluating any futures trade or funding arbitrage:
Identify the sign, interval, next settlement and whether the displayed rate is indicative or already settled.
Compare like-for-like periods and actual payments. A recent rate is not a promise that the next one will match.
Verify the underlying asset, position values and settlement schedules, then include the costs of opening and closing.
For an illustrative long at 10x, +0.05% costs 0.5% of initial margin for one settlement when notional is unchanged. Total strategy capital also includes the hedge and reserves.
Open accounts early and complete KYC. Links go to signup / invite pages. This is not an endorsement of any venue — verify availability in your country.
Calculate cash amounts for all payments over the holding window, then separately estimate fees, execution and spread changes. Calculate return from the final result relative to all committed capital: spot, margin and reserves.
FAQ
How often is funding paid?
The contract determines the interval, which can change. Hourly, four-hour and eight-hour settlements exist. Check the current schedule and next settlement for each position.
Who pays funding: longs or shorts?
At a positive rate, longs pay shorts; at a negative rate, shorts pay longs. In an illustrative linear contract, +0.01% on $10,000 notional means $1.00 for one settlement.
Can you receive funding without price risk?
A hedge reduces directional exposure, but basis changes, incomplete execution and liquidation of one side remain possible. Fees and rate changes can also outweigh funding received.
How do you calculate funding over a month?
Sum payments for the actual settlements. An illustrative $10,000 long at a constant +0.01% every 8 hours pays $90 for 90 settlements over 30 days. That is 0.9% of notional, not a forecast of rates or capital returns.